The Fixed-Cost Fallacy: Andrew Zezas on Why CFOs Should Stop Treating Real Estate Like A Utility Bill
By
Martin Daks, Editor, CFO Intelligence Magazine
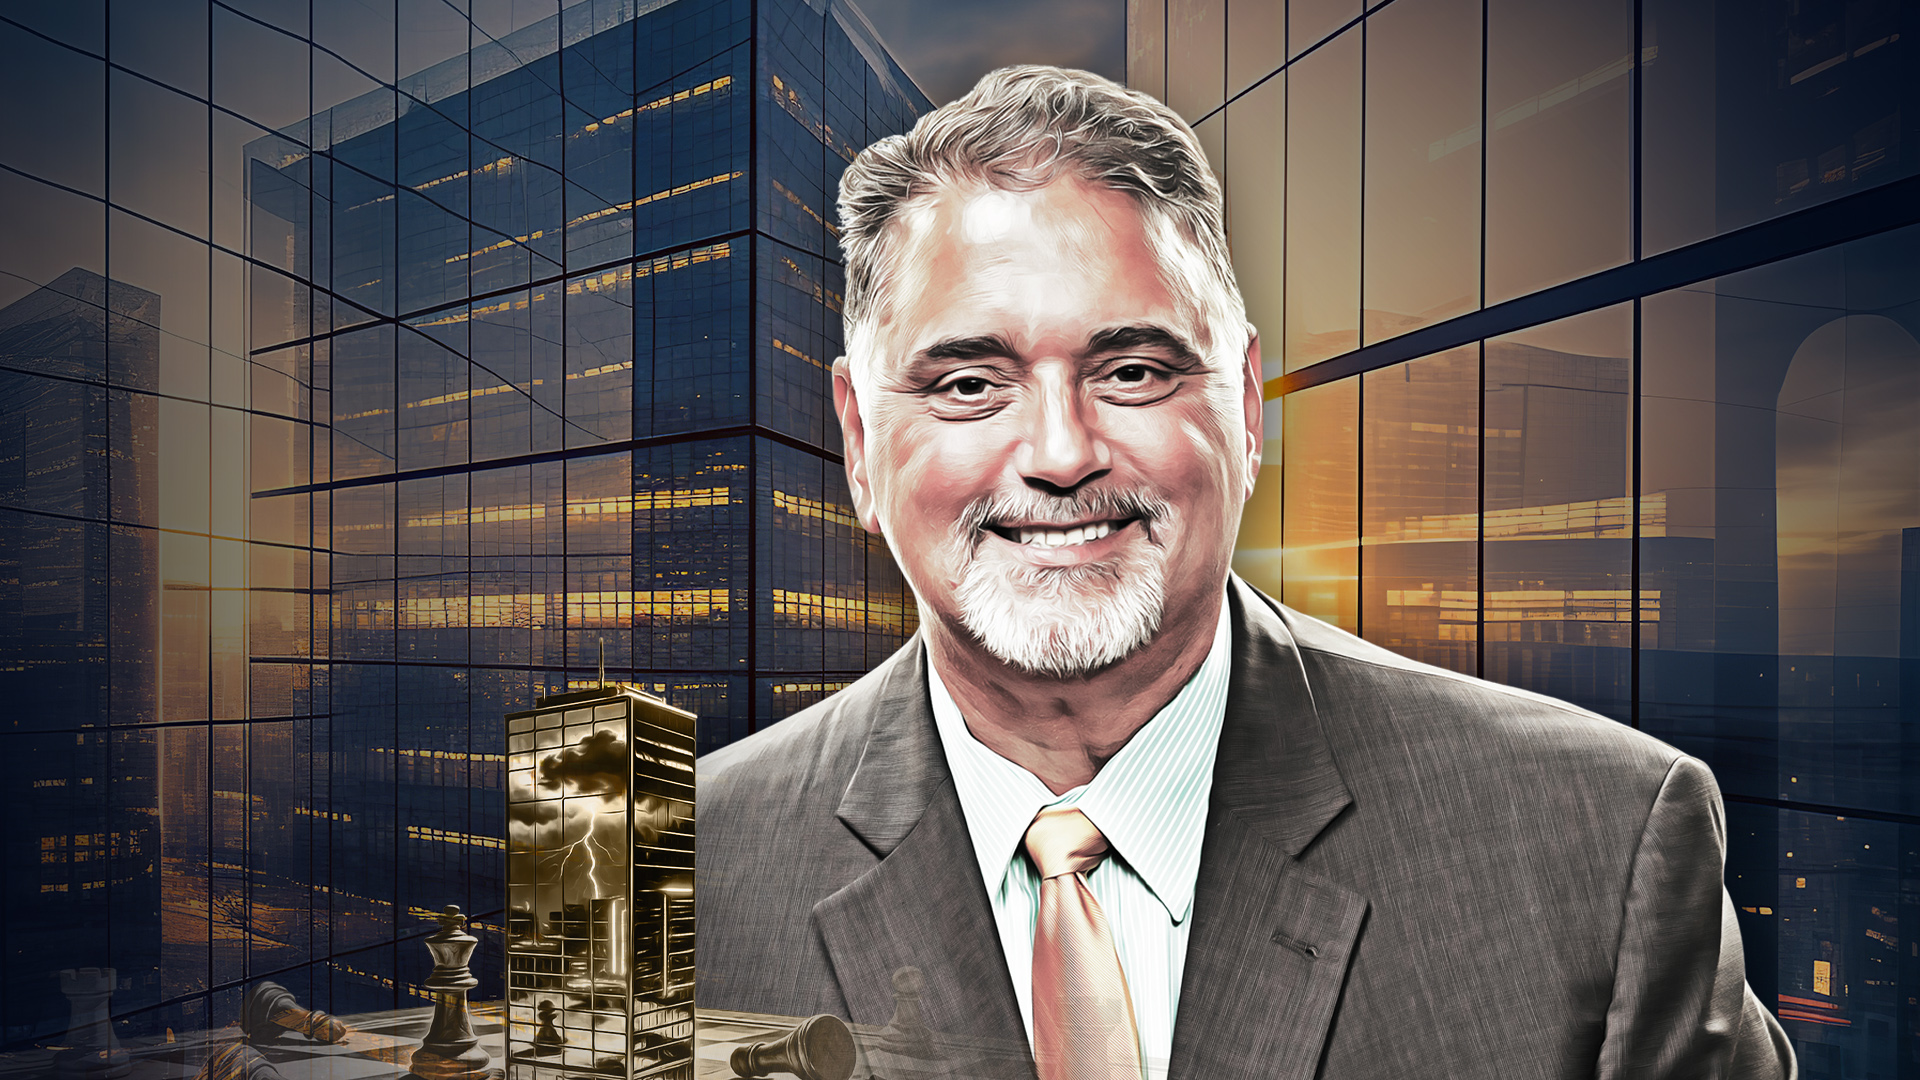
There is a particular kind of headache that lives on a CFO's desk and refuses to go away. It doesn't show up in the monthly close. It doesn't trip a covenant. It just sits there, quietly, for years at a time — a fifteen-year lease signed under one set of assumptions, now operating under a completely different set of realities.
Consider the arithmetic every finance chief is currently running. Hybrid work has permanently changed how much square footage a workforce actually needs. M&A activity — still brisk despite rate volatility — routinely leaves acquiring companies holding two headquarters, three distribution centers, and a patchwork of leases that were never designed to be integrated. Regional expansion into new labor markets happens in months; the real estate that supports it was often signed in decades. Strategy, in other words, now pivots on a dime. Commercial real estate does not.
"Every other line item on a CFO's balance sheet gets stress-tested constantly," says Andrew Zezas, founder and president of Real Estate Strategies Corporation (RealStrat), a corporate real estate strategy and advisory firm that has spent more than two decades working with CFOs, COOs, and boards across North America. "Real estate almost never does. It gets signed, it gets filed away, and it gets treated like a utility bill — a fixed cost you pay and forget about. That's the single biggest blind spot I see in corporate finance today."
It's a blind spot with real consequences. Real estate is frequently the second- or third-largest expense category on a company's income statement, trailing only payroll and, in some sectors, cost of goods sold. And yet, unlike payroll or COGS, it rarely gets the kind of active, ongoing strategic management that a CFO would insist on for any other major cost center. Once the ink dries on a lease, it tends to disappear into the background of corporate life — a sunk commitment rather than a lever that can be pulled.
Zezas has built a career, and a firm, around changing that.
The Architect, Not the Broker
It would be easy to mistake RealStrat for a commercial real estate brokerage. Zezas is quick to correct that impression, and not out of semantic vanity. The distinction, he argues, is the whole point.
"A broker's job, traditionally, is to find you a space and close a transaction," Zezas explains. "That's a real skill, and it has its place. But it's fundamentally reactive — it starts from the assumption that you already know what you need, and the only question left is where to find it. We start several steps earlier than that. Before we talk about a single square foot of space, we want to understand where the business is going. What does the balance sheet need to look like in three years? Five years? What's the capital plan? What's the workforce plan? What's the M&A pipeline? Real estate strategy has to be downstream of that thinking, not disconnected from it."
That philosophy is the foundation of what RealStrat calls portfolio strategy — treating a company's occupied real estate not as a fixed collection of individual leases to be renewed or renegotiated one at a time, but as a single, living ecosystem that should flex in step with the business itself. Under this model, a headquarters lease in one city, a distribution facility in another, and a satellite office in a third are not three unrelated transactions handled by three different regional brokers on three different timelines. They're interconnected variables in one enterprise-wide financial model.
"When you map the whole portfolio against the company's actual operating and financial goals — not just against expiration dates — you start to see things you'd otherwise miss," Zezas says. "Maybe you're overpaying for space in a market where headcount is shrinking, while underinvesting in a market where the company is about to make a major push. Maybe there's an opportunity to consolidate three leases into one and free up capital for something the business actually needs right now. None of that shows up if you're managing real estate lease by lease, market by market, in isolation."
This is where the "living ecosystem" framing does real analytical work, rather than serving as a marketing flourish. RealStrat's engagements typically begin not with a site tour, but with a deep dive into a company's three-to-five-year strategic and financial plan — the same kind of horizon a CFO uses for capital allocation, workforce planning, and investor guidance. Real estate decisions are then reverse engineered from that plan, rather than treated as a parallel process that happens to intersect with it occasionally at renewal time.
The approach has proven particularly relevant in the post-2020 environment, when the ground beneath corporate real estate decisions has shifted repeatedly and often unpredictably. Hybrid and remote work reshuffled space requirements almost overnight. Interest rate volatility changed the calculus on sale-leasebacks and capital deployment. A wave of consolidation-driven M&A has left many companies managing real estate portfolios that were assembled by acquisition rather than by design. Through all of it, Zezas has pushed the same core argument: the companies that treat real estate as a strategic instrument — actively managed and continuously re-mapped against corporate goals — come out ahead of the ones that treat it as background noise.
"CFOs already think this way about capital structure, about working capital, about nearly everything else on the balance sheet," Zezas says. "Real estate just hasn't caught up yet. Part of what we do is help it catch up."
The Pain Point That Wouldn't Go Away
It's a short walk from that observation to the origin story behind CFO Intelligence Magazine — and it's a walk Zezas has made many times in conversation — because it explains why a real estate strategist ended up building a media and intelligence platform for finance executives.
The pattern, as Zezas describes it, kept repeating itself across engagements. RealStrat would be brought in to fix a real estate problem, and the conversation with the CFO would inevitably widen. The lease renewal or portfolio restructuring at hand was rarely the CFO's only unresolved strategic friction point. It was simply the one that had become urgent enough, or expensive enough, to force action. Underneath it, in nearly every case, sat a broader frustration: a lack of high-quality, peer-level intelligence about how other finance leaders were actually solving similar problems.
"CFOs are some of the most isolated senior executives in a company," Zezas says. "The CEO has a board. Sales has industry conferences and a whole ecosystem of benchmarking data. But a CFO facing a hard capital allocation decision, or a real estate stagnation problem, or a restructuring question, often doesn't have an easy way to find out how a peer at a comparable company actually navigated the exact same thing. What exists is a lot of vendor-driven content dressed up as thought leadership, and a lot of generic finance media that doesn't get close enough to the operational specifics that actually matter."
That gap — between the volume of content aimed at CFOs and the scarcity of content genuinely useful to CFOs — is the thesis CFO Intelligence was built on. And it is, Zezas candidly says, the same thesis that built RealStrat in the first place.
"RealStrat exists because we got obsessive about understanding the specific operational friction a CFO experiences around real estate — not real estate in the abstract, but the actual, granular problems: a lease that no longer matches the business, a portfolio nobody has looked at holistically, a capital decision that's being made with incomplete information," Zezas explains. "Once you understand a pain point at that level of specificity, you can build a real solution for it instead of a generic one. CFO Intelligence came from asking the same question about a different pain point: What if the friction isn't physical assets, it's the absence of a genuine peer network and unfiltered, practitioner-level intelligence? If you take that problem as seriously as we took the real estate problem, you end up building something very different from the standard finance media outlet."
The result is a platform explicitly built around peer-to-peer insight rather than top-down commentary — CFOs and senior finance leaders speaking to the specific, tactical realities of the job, in a format designed for people who don't have time for filler. It's a deliberately narrow mandate, and Zezas argues that the narrowness is the value.
"We didn't want to build something that tries to be everything to every finance professional," he details. "We wanted to build something that a sitting CFO, in the middle of a hard week, would actually find useful — the way a good advisor is useful, not the way a press release is useful."
Two Businesses, One Operating Principle
It would be a mistake to read CFO Intelligence as a diversification play, a side project loosely adjacent to RealStrat's core business. Zezas frames it instead as the same operating principle, applied to a different category of asset.
"RealStrat solves operational friction through physical asset strategy — taking a static real estate portfolio and turning it into something dynamic, something that actually moves with the business," he says. "CFO Intelligence solves a parallel kind of friction through intellectual and network strategy — taking the static, one-directional way most finance content gets delivered and turning it into something that moves with the actual needs of the person reading it. Different asset class. Same instinct: get uncomfortably close to the problem before you try to solve it."
It's an instinct that shows up repeatedly in how Zezas talks about both ventures — a resistance to treating any part of the CFO's world as fixed, background, or beyond examination. Real estate portfolios that other advisors would leave alone until the lease expiration forces a decision. Finance media that other publishers would leave in its familiar, vendor-adjacent format because that's simply how the category has always worked. In both cases, the starting premise is the same: things that look permanent are usually just things nobody has bothered to re-examine recently.
For CFOs navigating a period when nearly every other input to their job — capital costs, workforce structure, deal flow, supply chains — has become more volatile and less predictable, that premise carries a certain logic. The tools they use to manage the business should be at least as dynamic as the business itself. That applies to the buildings a company occupies. Zezas would argue it applies equally to where and how a CFO goes looking for the next good idea.
"The CFOs who do well over the next decade aren't going to be the ones who found one clever real estate deal or read one useful article," Zezas says. "They're going to be the ones who built the habit of questioning what's supposedly fixed — their portfolio, their network, their information sources — on a regular basis. That's really all either of these businesses is trying to help with."
Consider the arithmetic every finance chief is currently running. Hybrid work has permanently changed how much square footage a workforce actually needs. M&A activity — still brisk despite rate volatility — routinely leaves acquiring companies holding two headquarters, three distribution centers, and a patchwork of leases that were never designed to be integrated. Regional expansion into new labor markets happens in months; the real estate that supports it was often signed in decades. Strategy, in other words, now pivots on a dime. Commercial real estate does not.
"Every other line item on a CFO's balance sheet gets stress-tested constantly," says Andrew Zezas, founder and president of Real Estate Strategies Corporation (RealStrat), a corporate real estate strategy and advisory firm that has spent more than two decades working with CFOs, COOs, and boards across North America. "Real estate almost never does. It gets signed, it gets filed away, and it gets treated like a utility bill — a fixed cost you pay and forget about. That's the single biggest blind spot I see in corporate finance today."
It's a blind spot with real consequences. Real estate is frequently the second- or third-largest expense category on a company's income statement, trailing only payroll and, in some sectors, cost of goods sold. And yet, unlike payroll or COGS, it rarely gets the kind of active, ongoing strategic management that a CFO would insist on for any other major cost center. Once the ink dries on a lease, it tends to disappear into the background of corporate life — a sunk commitment rather than a lever that can be pulled.
Zezas has built a career, and a firm, around changing that.
The Architect, Not the Broker
It would be easy to mistake RealStrat for a commercial real estate brokerage. Zezas is quick to correct that impression, and not out of semantic vanity. The distinction, he argues, is the whole point.
"A broker's job, traditionally, is to find you a space and close a transaction," Zezas explains. "That's a real skill, and it has its place. But it's fundamentally reactive — it starts from the assumption that you already know what you need, and the only question left is where to find it. We start several steps earlier than that. Before we talk about a single square foot of space, we want to understand where the business is going. What does the balance sheet need to look like in three years? Five years? What's the capital plan? What's the workforce plan? What's the M&A pipeline? Real estate strategy has to be downstream of that thinking, not disconnected from it."
That philosophy is the foundation of what RealStrat calls portfolio strategy — treating a company's occupied real estate not as a fixed collection of individual leases to be renewed or renegotiated one at a time, but as a single, living ecosystem that should flex in step with the business itself. Under this model, a headquarters lease in one city, a distribution facility in another, and a satellite office in a third are not three unrelated transactions handled by three different regional brokers on three different timelines. They're interconnected variables in one enterprise-wide financial model.
"When you map the whole portfolio against the company's actual operating and financial goals — not just against expiration dates — you start to see things you'd otherwise miss," Zezas says. "Maybe you're overpaying for space in a market where headcount is shrinking, while underinvesting in a market where the company is about to make a major push. Maybe there's an opportunity to consolidate three leases into one and free up capital for something the business actually needs right now. None of that shows up if you're managing real estate lease by lease, market by market, in isolation."
This is where the "living ecosystem" framing does real analytical work, rather than serving as a marketing flourish. RealStrat's engagements typically begin not with a site tour, but with a deep dive into a company's three-to-five-year strategic and financial plan — the same kind of horizon a CFO uses for capital allocation, workforce planning, and investor guidance. Real estate decisions are then reverse engineered from that plan, rather than treated as a parallel process that happens to intersect with it occasionally at renewal time.
The approach has proven particularly relevant in the post-2020 environment, when the ground beneath corporate real estate decisions has shifted repeatedly and often unpredictably. Hybrid and remote work reshuffled space requirements almost overnight. Interest rate volatility changed the calculus on sale-leasebacks and capital deployment. A wave of consolidation-driven M&A has left many companies managing real estate portfolios that were assembled by acquisition rather than by design. Through all of it, Zezas has pushed the same core argument: the companies that treat real estate as a strategic instrument — actively managed and continuously re-mapped against corporate goals — come out ahead of the ones that treat it as background noise.
"CFOs already think this way about capital structure, about working capital, about nearly everything else on the balance sheet," Zezas says. "Real estate just hasn't caught up yet. Part of what we do is help it catch up."
The Pain Point That Wouldn't Go Away
It's a short walk from that observation to the origin story behind CFO Intelligence Magazine — and it's a walk Zezas has made many times in conversation — because it explains why a real estate strategist ended up building a media and intelligence platform for finance executives.
The pattern, as Zezas describes it, kept repeating itself across engagements. RealStrat would be brought in to fix a real estate problem, and the conversation with the CFO would inevitably widen. The lease renewal or portfolio restructuring at hand was rarely the CFO's only unresolved strategic friction point. It was simply the one that had become urgent enough, or expensive enough, to force action. Underneath it, in nearly every case, sat a broader frustration: a lack of high-quality, peer-level intelligence about how other finance leaders were actually solving similar problems.
"CFOs are some of the most isolated senior executives in a company," Zezas says. "The CEO has a board. Sales has industry conferences and a whole ecosystem of benchmarking data. But a CFO facing a hard capital allocation decision, or a real estate stagnation problem, or a restructuring question, often doesn't have an easy way to find out how a peer at a comparable company actually navigated the exact same thing. What exists is a lot of vendor-driven content dressed up as thought leadership, and a lot of generic finance media that doesn't get close enough to the operational specifics that actually matter."
That gap — between the volume of content aimed at CFOs and the scarcity of content genuinely useful to CFOs — is the thesis CFO Intelligence was built on. And it is, Zezas candidly says, the same thesis that built RealStrat in the first place.
"RealStrat exists because we got obsessive about understanding the specific operational friction a CFO experiences around real estate — not real estate in the abstract, but the actual, granular problems: a lease that no longer matches the business, a portfolio nobody has looked at holistically, a capital decision that's being made with incomplete information," Zezas explains. "Once you understand a pain point at that level of specificity, you can build a real solution for it instead of a generic one. CFO Intelligence came from asking the same question about a different pain point: What if the friction isn't physical assets, it's the absence of a genuine peer network and unfiltered, practitioner-level intelligence? If you take that problem as seriously as we took the real estate problem, you end up building something very different from the standard finance media outlet."
The result is a platform explicitly built around peer-to-peer insight rather than top-down commentary — CFOs and senior finance leaders speaking to the specific, tactical realities of the job, in a format designed for people who don't have time for filler. It's a deliberately narrow mandate, and Zezas argues that the narrowness is the value.
"We didn't want to build something that tries to be everything to every finance professional," he details. "We wanted to build something that a sitting CFO, in the middle of a hard week, would actually find useful — the way a good advisor is useful, not the way a press release is useful."
Two Businesses, One Operating Principle
It would be a mistake to read CFO Intelligence as a diversification play, a side project loosely adjacent to RealStrat's core business. Zezas frames it instead as the same operating principle, applied to a different category of asset.
"RealStrat solves operational friction through physical asset strategy — taking a static real estate portfolio and turning it into something dynamic, something that actually moves with the business," he says. "CFO Intelligence solves a parallel kind of friction through intellectual and network strategy — taking the static, one-directional way most finance content gets delivered and turning it into something that moves with the actual needs of the person reading it. Different asset class. Same instinct: get uncomfortably close to the problem before you try to solve it."
It's an instinct that shows up repeatedly in how Zezas talks about both ventures — a resistance to treating any part of the CFO's world as fixed, background, or beyond examination. Real estate portfolios that other advisors would leave alone until the lease expiration forces a decision. Finance media that other publishers would leave in its familiar, vendor-adjacent format because that's simply how the category has always worked. In both cases, the starting premise is the same: things that look permanent are usually just things nobody has bothered to re-examine recently.
For CFOs navigating a period when nearly every other input to their job — capital costs, workforce structure, deal flow, supply chains — has become more volatile and less predictable, that premise carries a certain logic. The tools they use to manage the business should be at least as dynamic as the business itself. That applies to the buildings a company occupies. Zezas would argue it applies equally to where and how a CFO goes looking for the next good idea.
"The CFOs who do well over the next decade aren't going to be the ones who found one clever real estate deal or read one useful article," Zezas says. "They're going to be the ones who built the habit of questioning what's supposedly fixed — their portfolio, their network, their information sources — on a regular basis. That's really all either of these businesses is trying to help with."
0 Comments